Dhaka Tribune: How do you describe the current relationship between Bangladesh and India? Do you find any irritants in the relationship? If so, what are those and how could those be overcome?
Samir Saran: Both India and Bangladesh have in recent years strived to overcome many of the legacy issues in their relationship. Today, we have an opportunity to strengthen our engagement even further. This requires the polity and people of the two countries to achieve closure on some irritants that continue to fester, especially the Teesta water sharing arrangement. New Delhi will need to make an extra effort to resolve India’s internal contradictions and move ahead with the agreement that is a real and an emotive issue for the people of Bangladesh. A fresh approach to bilateral trade relations is also needed. Bangladesh businesses and society need to see tangible gains from India’s rise and trade terms need to be more favorable to ensure equity on this front.
DT: You said on Wednesday (March 13) that the relationship between Dhaka and Delhi is at its best. Do you think that there are areas where both countries can work to further the relationship?
SS: I had remarked that the government to government relationship between the two countries were strong and robust and had achieved a new high in the recent past. I had also mentioned that for a truly sustainable and strong relationship, it is necessary to invest in creating new constituencies that can take the relationship forward. We have to ensure that our businesses, media and research institutions collaborate with greater intensity and conviction and provide a new impetus to this very important bilateral. The two countries must also support purposeful conversations on trade and infrastructure connectivity in the region, within and outside regional institutions such as the Indian Ocean Rim Association and the BIMSTEC. The common determination of the two countries to achieve the Sustainable Development Goals (SDGs) offers a possibility for them to collaborate in this journey. Our homegrown solutions can be shared with each other and also with the larger developing world. Technology sector, smart cities, rural transformations and the blue economy potential of the region, all offer new opportunities for partnership.
DT: Many people in Bangladesh tend to believe that India tries to dominate over Bangladesh and makes effort to intervene into the internal affairs of the country. Are they right? Do you think the relationship is based on mutual respect and interest?
SS: India has and always will respect equality in international relations and respect for sovereignty. It does not interfere in the internal affairs of others and has always adhered to international law and norms of state behaviour in its relationship with other countries. This is true of Bangladesh as well. When India lost a maritime dispute to Bangladesh in 2014, under a dispute resolution proceeding, it respected that verdict in contrast to some other countries in the region which have rejected such processes when they have gone against them. The relationship is certainly built on trust and mutual respect as can be seen in the process followed to resolve the border issue as well. All nations make choices based on their self-interest and this is true for India and Bangladesh as well.
DT: Do you agree with those people who suggest that if the Teesta water sharing agreement is signed, border killing is brought to zero and the trade imbalance that is heavily in favour of India are addressed, Bangladesh-India ties will be further strengthened?
SS: Without responding to the subjective allegations, let me first put on record that the India-Bangladesh ties are indeed strong. This is not to say that issues do not remain. The solutions are more often hindered because of domestic politics in India and Bangladesh, and less so for the lack of political will at the level of the leadership of the two countries. I am sure that we will see a new momentum in Delhi to address all outstanding issues after the general elections in May. I have always favoured soft borders, they should be a location that enhances commerce and value creation. Hard boundaries are a tragic consequence of old mindsets. Trade issues and Teesta water sharing arrangement must be addressed at the earliest to the satisfaction of all.
DT: What are the areas both the neighbours should work on in the coming days for the benefits of their peoples?
SS: Both India and Bangladesh seek development and economic growth for their large and young populations. We must do this at a time when new technologies are changing the way we work and live, and we must do this in a carbon constrained world. These are new challenges for both of us. With similar demographics and development outlooks, these should be the key area of cooperation going forward. On the regional front, India and Bangladesh should also now start imagining a political and economic order for the Indo-Pacific. Both countries have an interest in sustaining a rules based order in the region, both have increasing stakes in a favourable and stable external environment.
DT: There is a perception in Bangladesh that the Indian government favours Awami League. Should it be the case? Should Delhi not work with the government of the day?
SS: India and Indians respect the democratic choices of the people of Bangladesh. While Delhi will maintain good relations with all political parties, it will naturally work with the government in charge of the country. Having said this, it is time that we engage with Bangladesh and its citizens and institutions more robustly. Diplomacy today is also about engaging with individual and communities effectively.
How do you judge China’s approach to Eurasia through the Belt and Road policies?
Samir Saran: China is the first country in recent times that has created a blue print which recognises that Europe and Asia are part of one single landmass. Beijing has created intermediate linkages for this “supercontinent’s” markets and communities. As China moves up the industrial value chain, it seeks wealthy European markets as a key consumer of high-end exports. On the other hand, it views smaller states in East Europe, West and Central Asia and South Asia as suppliers of raw materials, geographies for new transportation networks, and dependant markets for its exports of goods, services and labour.
China and Russia have one binding cause — disdain for the international order established by the West.
It has also found, not surprisingly, a willing partner in Russia — whose residual influence in Central Asia and Eastern Europe makes it a key player in an integrated Eurasia. Both countries have one binding cause — disdain for the international order established by the West. With Russia currently on its side (although this is not a certainty over the long term), the Middle Kingdom is able to set the rules of trade, economic development and security in these regions. Its sizable influence in regional organisations like the SCO, the 16+ 1initiative and the AIIB also provide China the institutional leverage to achieve this.
China’s attempts to integrate these continents, however, will not be free of political friction. Some of the sub-regions that inhabit Eurasia — think South Asia — already possess existing balance of power arrangements. In effect, China seeks to disregard these, and co-opt nation states into its Belt and Road network. Already, larger states, such as those in West Europe and India have voiced reservation and disapproval. In India’s case, such protestations led to a prolonged military stand-off in the Himalayas in 2017. These powers will gradually develop alternative propositions and arrangements for their sub-regions and indeed for the supercontinent. The implications of this contest, the changing coalitions and evolving politics and trade relations will define the coming decades for Eurasia.
Can India escape China’s orbit for economy and technology in the future?
SS: The resilience of the international system has begun to strain just as India is “emerging” as a global power. The erstwhile providers of security and global public goods, such as the US and Europe, appear to be looking inwards even as India requires technology and finance. China meanwhile, is in the midst of a multibillion dollar geo-economics thrust that is capable of both underwriting India’s economic growth and undermining its influence in regional and global affairs.
In the coming decades, India faces the proverbial catch-22 situation with China. New Delhi must learn how to stand firm against China in the political and security realm, while courting it for new investments and growth opportunities. So far the results are mixed on the latter. Bilateral trade remains a persistent irritant — with Chinese exports dominating the economic relationship. On the other hand, Chinese technology companies and venture capitalists are some of the leading investors in India’s budding technology industries.
Part of the answer will also lie in India’s domestic choices The returns from the economic reforms India undertook in the 1990’s are fast waning. India will have to undertake complex systemic reforms across its political and economic institutions if it is to reap the benefits of the fourth industrial revolution. And it will have to do so while providing employment and social mobility to the one of the world’s largest and youngest workforces.
India will have emerged as one of the worlds three largest economies by 2040, alongside the US and China.
The question therefore is not whether India can “escape China’s orbit.” By most estimates, India will have emerged as one of the worlds three largest economies by 2040, alongside the US and China. As it rises, Delhi will provide development solutions to the rest of the emerging world. The question therefore, is whether India can provide effective democratic alternatives for growth and development in the 21st century.
Can the EU contribute to India’s frontier technologies and sustainable growth?
SS: The EU can do much more than contribute to India’s economic and technological growth. Both these actors are geographical pillars of the Eurasian landmass, and invested actors in the Indo-Pacific. Both share a commitment to liberal democracy and market based economics (to varying degrees). And both actors believe in supporting a rules based international order through robust institutions.
The EU and India share a commitment to liberal democracy and market based economics.
These realties make India and the EU key partners in shaping a 21st century order. This realisation is already dawning on the EU. Just last year the bloc released its “elements for a strategy with India”— the first since 2004. And both sustainable development and innovation are key pillars of this strategy. While currently, India may not possess its own coordinated strategy for the EU, this is not likely to be a permanent state of affairs.
The overall state of the international order certainly adds a fresh impetus to the EU-India partnership. With both China and the US increasingly embracing their own unique forms of nationalism, the world is in need of ‘issue’ and ‘interests’ based alliances and coalitions capable of sustaining multilateralism. In fact, between the EU and India lies an opportunity to find common grounds and positions vis-a-vis both China and the US. Even as the EU and India can, for example, carry forward the Paris Climate Change agenda despite the US’ withdrawal, they can together address and moderate China’s state sponsored mercantilist economic policy.
We are currently in a moment in time, where the EU is roiled by populist politics and India itself is still a relatively small economy preoccupied with nation building. Nevertheless, long term trends favour a strong relationship between the two. It is time for both actors to act rapidly on this opportunity.
This year’s Raisina Dialogue looked ahead of the disruptions that have agitated global politics for the past few years and interrogated what they mean for an emerging world order. As the international system rapidly drifts away from the moorings of its Atlantic origin, its future will be decided by the complex interactions among new actors, voices and demands. After a period of relative unipolarity at the turn of the century, we are entering a world that is not only multipolar but also ‘multiconceptual’.
Why multiconceptual? For one thing, the concentration of economic wealth is “relentlessly shifting eastwards,” as noted by Mark Sedwill, the UK’s National Security Adviser. This transformation will certainly create new ‘poles’ of power—India and China chief among them. It will simultaneously diminish the influence of extant powers. Spain’s Minister for Foreign Affairs Joseph Borell alluded to this reality when he called on Europe to “influence or be influenced”.
Beyond the diffusion of economic power, the world is also grappling with an explosion of new actors, values and interests—from powerhouse cities to powerful multinationals and networked civil society groups.
This global complexity is straining the ability of the international community to adapt and respond to the momentous social and economic transformations that are currently underway. Every year, dire warnings about the impact of climate change pass by unheeded. The global economy is being increasingly driven by digitisation and associated technologies, with returns accruing mainly to owners of capital. Economic opportunities and jobs for millions, on the other hand, are being lost to automation. Meanwhile, our institutions of governance are struggling to address tensions of inequality and identity.
Around the world societies are responding by taking solace in national solutions and populist prescriptions that promise to put local concerns ahead of global ones. Perhaps it is only natural that a period of geopolitical flux should coincide with a renewed emphasis on the power and authority of the state. The consequences of this trend for international norms and institutions, however, are dire. “The insecurity felt by millions will weaken respect for international law and institutions, human rights and the principles of collective security,” warned Norwegian Prime Minister Erna Solberg as she inaugurated the 2019 Raisina Dialogue.
More worryingly, the perception of exclusion reduces our collective capacity to arrive at a consensus. And in a world that is more interdependent—and more fragile—than ever before, finding solutions requires more, not less, international cooperation. How can multilateralism, then, be made relevant in a multiconceptual world?
To start with, we certainly require a new international framework to capture the diversity of reality, views and voices that exist today. Minister for External Affairs Sushma Swaraj said as much when she suggested that key public policy questions be asked in “villages and small towns, to school classrooms, and to vernacular media outlets.” She was alluding to the fact that the international system requires a new consensus which is more inclusive and diverse. It also requires a new ethos defined by the common interests and urges of the many, rather than the shared objectives and strategies of a few.
Second, the international community requires a new ‘new deal’. This is true both domestically and for global governance. The Washington Consensus is no longer relevant in the fourth industrial revolution. The twin forces of globalisation and technological change will create new winners even as they leave many behind. Designing inclusive economic models will require new policies capable of balancing sovereign compulsions and global interdependence. They will also require unlikely partnerships at the global level. There is no reason, for example, that the NATO and the SCO cannot have influential conversations on the Indo-Pacific or Afghanistan or, for that matter, the BRICS and the G7 cannot harmonise their diverse economic models and expectations from a global trading regime.
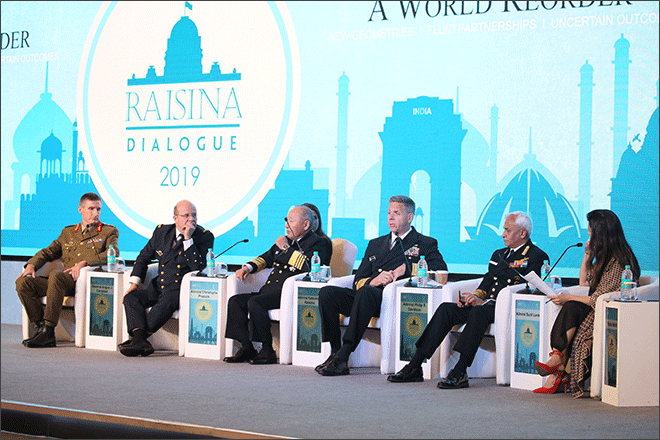
Source: PhotoLabs@ORF
Third, new coalitions and partnerships must emerge. French Secretary-General for European and Foreign Affairs Maurice Gourdault-Montagne said “issues based alliances will proliferate if the international order continues to fragment.” However, such coalitions, especially between those with shared values and interests, have a role to play in supporting the international order in its period of transition. Australian Minister for Foreign Affairs Marise Payne saw such potential in India, a country with which Australia could support a “rules-based order”. Such coalitions must be able to cut across geographies, issues and interests.
Fourth, global governance must account for new actors. Over 60 per cent of the world’s GDP is now generated in cities. The market capitalisation of the largest technology companies far exceeds the GDP of even significant countries. By this reckoning, Apple is bigger than Saudi Arabia. Solutions to big-ticket challenges like climate change and the future of work may well emerge from these networks of power and other key voices like think tanks and civil society organisations. Instituting new mechanisms for dialogue between such actors can create more effective global feedback loops.
Fifth, international institutions must reclaim some legitimacy. In the middle of the 20th century, the organising principle of ‘one country-one vote’ in international affairs resonated with many post-colonial societies. While global institutions have rarely proved truly democratic, it is evident that the key to legitimacy is a real distribution of decision making authority amongst stakeholders. India’s Foreign Secretary Vijay Gokhale warned that the “tussle between unilateralism and multilateralism” would continue unless international steering mechanisms are able to better capture today’s global realities.
Sixth, the international community must embrace informality. Formal global institutions can often be ineffective in responding to challenges that are sudden and complex. Informal coalitions and governance models, on the other hand, can summon the human and technological capital that is required to collaborate at scale. The global climate change agenda, for instance, is being quietly led by coalitions of cities from the global north and the global south. They are rapidly scaling and transferring innovation, ideas, resources and capital.
Seventh, the innocent appreciation of technology being benevolent and beneficial has changed the world over. Technology is now both a tool and an actor that can dramatically enhance quality of life and radically destabilise societies and nations. Foreign Secretary Gokhale captured the essence of this juxtaposition by suggesting that the rapid development of social sciences alongside science and technology is a prerequisite for ensuring that innovation benefits humankind. A new ethic of human engagement awaits discovery.
Last, though not the least, it is worth noting that securing geopolitical stability and protecting multilateralism will certainly require new stewardship. It is increasingly likely that in the coming years India will be a prime candidate for this role, even if only because India is a microcosm of the world at large. Rapid technological advances, a booming labour force and the imperative to develop in a resource-constrained world will define the ‘India story’ and, in turn, impact the future of billions in the developing world. Thus India presents a unique opportunity as an arena to resolve many of the world’s contradictions.
Source: PhotoLabs@ORF
India is a post-colonial state that has emerged as a vocal proponent of a liberal, rules-based international order. It is located at the intersection of Eurasia and the Indo-Pacific, two regions that will define the 21st century. And it has always been willing to navigate complexity by seeking shared objectives. Very few countries, for example, can claim to engage with powers like Russia and China while embracing a strategic partnership with the US. As Minister Swaraj noted in her address, “India’s engagement with the world is rooted in its civilisational ethos: co-existence, pluralism, openness, dialogue and democratic values.”
It is for this very reason that Dato Seri Anwar Ibrahim described India as “an enigma.” In many ways, the annual Raisina Dialogue is an attempt to deconstruct what makes it so and why this is relevant to the world. The feedback we have received from world leaders in the fields of politics, industry, media and civil society makes it clear that India’s choices matter more than ever before. Increasingly, the conversations that take place at the Raisina Dialogue are not only teasing out an Indian consensus on world affairs but a larger consensus capable of shaping a less unstable, more predictable world reorder.
The allocation for health of around INR 63,540 crore is about a 13% increase from last year. Much of it has been to PMJAY, the flagship scheme of the government, which saw allocation rise from INR 2,400 crore last year to INR 6,400 crore in the interim budget. Ayushman Bharat’s second arm, the HWCs also got considerable hike in budget allocation — from INR 1,200 crore to INR 1,600 crore. FSSAI as well as the National AIDS Programme have also seen improvements in allocation.
Photo: Atul Loke/Getty
However, an exclusive focus on PMJAY can result in a possible de-prioritisation of core health system functions, with slow-down or reduction of allocations under various heads, including NHM. Capital outlay on medical and public health, for example, has come down from 3047.67 crore in 2017-18 (actual) to 2391.33 crore in 2018-19 (RE) to 1675.90 crore in 2019-20. This can potentially impact health system’s capacity to expand in areas that need health services the most. Neglected areas can remain neglected unless there is specific focus. The budget document stated that of the 3,508 HWCs already operational, only 582 are in the aspirational districts, or the districts lagging in health development.
An exclusive focus on PMJAY can result in a possible de-prioritisation of core health system functions, with slow-down or reduction of allocations under various heads, including National Health Mission.
Lastly, it is easy to celebrate the INR 6,400 crore allocation, meant for around 50 crore PMJAY members. Still, the money allocated remains around INR 1,000 crore short of a conservative estimate of PMJAY spending this year. To put things in perspective, healthcare coverage to just around 35 lakh CGHS beneficiaries will cost the exchequer INR 3,000 crore, of which INR 2,850 crore was allocated in the interim budget. In addition, delays in payment of sanctioned amounts undermining efficiency of PMJAY remains a real risk, as with many health schemes. As of now, reports indicate that of the INR 2,400 crore allocated last year for PMJAY by the MoF, INR 1,000 crore has yet not been released, and that there are outstanding payments from the Centre to the States amounting to INR 1,700 crore under PMJAY. This can potentially impact the sustainability and effectiveness of the scheme.
It was decided by the government that India’s government health spending will be 2.5% of its GDP by 2025. At the current pace, it will be impossible. As a percentage share of total budget, the interim budget outlay on health was just 2.2%, below the figure in 2017-18, where the proportion of health outlay peaked under the Modi regime at 2.4%. Health in India needs significant additional resources, and not reallocation of existing resources. Ayushman Bharat becoming the flagship health initiative cannot and should not lead to a case of the government missing the forest for the trees. Without expansion of real health infrastructure, Ayushman Bharat will be just band-aid.
The Union Budget 2019 signals early forays into artificial intelligence by the Indian government with the announcement that a National Centre on AI will soon be set up. This centre will presumably work in close coordination with Centres of Research Excellence in Artificial Intelligence (COREs) that were first proposed by the NITI Aayog in its discussion paper: National Strategy for Artificial Intelligence. While the NITI Aayog identified five areas primed for AI intervention, namely healthcare, agriculture, education, smart cities and smart mobility, the Union Budget speech hints that four more priority areas have been identified.
In a manner now idiosyncratic of the Modi government, the Minister of Finance also announced plans for the creation of an ‘national AI portal.’ Details of what this portal will achieve or what it will be meant for remain unclear. Also missing from the budget are critical details around the quantum of investment in AI and automation technologies that are being planned.
Conspicuously missing from the budget are any references to digital payments or cyber security — both strong protagonists in Modi’s Digital India.
The Finance Minister’s speech also revealed ambitious plans to digitise one lakh villages over the next five years as a part of the Digital India programme by providing WiFi access to these villages. This initiative will be spearheaded by the Common Service Centres that now serve as nodal points of delivery for public utility services.
Conspicuously missing from the budget though are any references to digital payments or cyber security — both strong protagonists in Modi’s Digital India. This absence will likely be felt by Indian tech companies who for a few years now have been demanding economic relief for domestic players to level the playing field and compete with the seemingly limitless cash inflow that US and Chinese tech startups seem to be riding on.
While the defence budget has been pegged at INR 3.05 lakh crore, an increase in absolute terms, the percentage of the GDP used for India’s defence for the year 2019-2020 remains at the measly 1.5% mark, still very low for any effective modernisation to take place. The interim finance minister, in his budget speech, has stated that the current defence personnel will see a rise in the Military Service Pay (MSP), while at the same time allocating funds for special allowances of Air Force and naval personnel who are stationed in high-risk zones. Apart from this funding of the military, the government has also earmarked a separate INR 35,000 crore as part of its OROP pension payments, in line with the BJP election manifesto. However, this defence budget still does not take into account the modernisation needs of the country, pegging only INR 1.08 lakh crore for new weapon systems, while the day-to-day expenses have been given a budget of INR 2.10 lakh crore.
This budget, while being touted as the largest increase in the defence budget of India, still reveals the fact that the Indian military is not being given enough room to upgrade its current equipment to keep pace with the rapid modernisation of the Chinese military. The budget highlights the fact that the government is only willing to keep its military functioning at the level it already is, not taking into account the asymmetry between itself and its neighbours in terms of both technology and equipment possessed. While there is no doubt that this year’s budget is a step forward in the right direction with more money being pooled in the upkeep of the military, serious attention needs to be paid to the slow speeds of modernisation of the military’s resources, which will prove to be a major factor in the coming years, in a time where the Chinese have begun downsizing and modernising and indigenising their equipment to meet the new threats of both the present and the future.
This budget, while being touted as the largest increase in the defence budget of India, still reveals the fact that the Indian military is not being given enough room to upgrade its current equipment to keep pace with the rapid modernisation of the Chinese military.
Prime Minister Narendra Modi addresses a joint session of the United States Congress at the US Capitol, 8 June 2016, Washington, DC. Photo: Mark Wilson/Getty
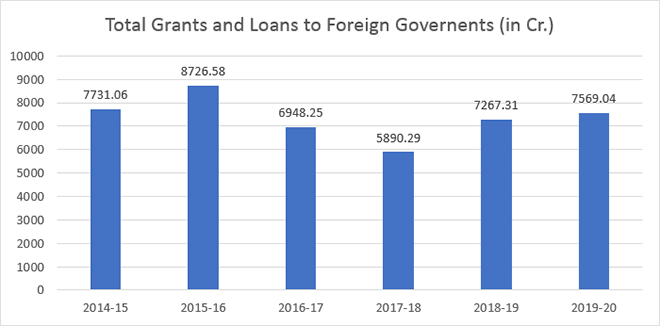
Compared to an allocation of INR 12,620 crore in 2014-15, the overall grant to the MEA in 2018-19 is INR 16,061 crore.
India’s allocation towards economic diplomacy has steadily crossed the USD 1 billion mark.With India already contributing nearly 15% to global growth, it must interrogate the consequences of its development partnerships more closely as allocations rise over the next decade.
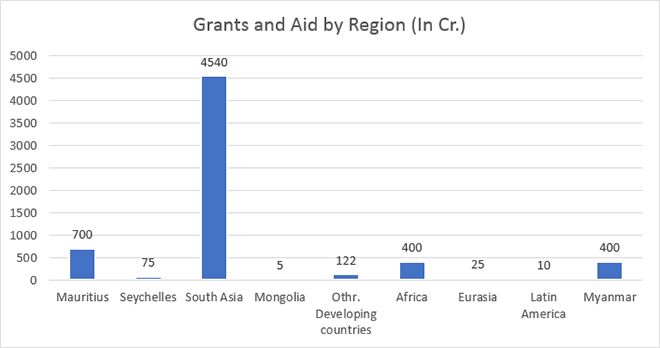
Two notable heads this year are aid to the Maldives and the Chabahar port. Following the establishment of a friendlier government in Male, India has more than quintupled its aid to Maldives — from INR 109 crore in 2018-19 in the original estimate, to INR 440 crore in the revised 2018-19 estimate, and to INR 575 crore this year. And continuing a new practice from last year, India has allocated INR 150 crore for the development of the Chabahar port.
These investments reveal India’s crucial connections to both the Indo-Pacific and the Eurasian landmass. However, while South Asian states receive the bulk of India’s economic assistance, India’s aid to Eurasia stands at INR 25 crore this year.
India’s investments in regional institutions also remains unfortunately low: INR 8 crore each for the SAARC and BIMSTEC Secretariat. While the BIMSTEC budget has doubled over the past two years, it remains insufficient to create effective human or technical capacity in the institution.
Over all, the 2019-20 Budget makes clear that India must recalibrate its approach to economic diplomacy in the region, especially given its domestic constraints.
For one thing, India must begin to identify priority sectors and States — especially in the Indo-Pacific and Eurasia. Development projects that create social and economic value for local communities and where India has a comparative advantage will be key. Supporting institutions like BIMSTEC and the IORA will also be important.
Second, convincing India’s private sector to invest in the infrastructure needs of developing countries will also be crucial. Indian Overseas Direct Investment in developing countries is still limited. Budgetary support by way of concessional financing for Indian companies investing in strategic infrastructure projects abroad also remains low.
Third, India’s concessional LoC framework must be made more competitive and transparent. Many privately admit that loans are arbitrarily granted to a select few Indian actors. There is also little available data on the economic benefits that accrues to India.
Fourth, plugging India’s capital gap will require imaginative collaboration with international donors. India must explore multilateral cooperation mechanisms with the US, the EU, Japan and Australia have all announced new economic initiatives in the Indo-Pacific and Eurasia.
Given that India will emerge as one of the largest sources of development finance in the coming years, it is time for the Government to release a white paper on how development partnerships can advance India’s economic and strategic interests.
Education: Less money to State institutes and technical colleges
The Interim Budget 2019 allocated INR 93,847.64 crore to education, which is although the largest till date with about a 10% increase from last year’s budget allocation — it is still only about 3.3% of the GDP. While the increase in allocation is a good sign, it has again failed to target the recommended 6% of the GDP required for India to inch closer to the Agenda 2030 of Sustainable Development Goals of the UN. Unlike last year, this year’s budget speech gave little importance to education as a priority sector for the economic development of the country.
Of the total budgetary allocation, school education yet again received the highest revenue of INR 56,386.63 crore, up from 50,000 crore in 2018-19. The National Education Mission (which comprises the Samagra Siksha Abhiyan for school education from pre-primary to class 12 and teacher training programmes) saw the maximum outlay of INR 36,472 crore, up from INR 31,212 crore in 2018-19. Although this is an increase, it is not enough to address the issues in school education, which has a massive near-perfect enrollment rate. Allocation to mid-day meal scheme that is known to increase attendance and improve health among children has seen paltry increase of INR 500 crore from last year. Most disheartening is to see a reduced outlay of about INR 87 crore for central schemes such as National Scheme for Incentive to Girl Child for Secondary Education, National Means cum Merit Scholarship Scheme, National Award to Teachers and Digital India e-learning.
While the increase in allocation is a good sign, it has again failed to target the recommended 6% of the GDP required for India to inch closer to the Agenda 2030 of Sustainable Development Goals of the UN. Unlike last year, this year’s budget speech gave little importance to education as a priority sector for the economic development of the country.
As for higher education, it has yet again failed to garner the attention of the policymakers. This year’s interim budget allocated INR 37,461 crore, which is a small increase of about INR 2,000 crore for 903 universities, 39,050 colleges and 10,011 standalone institutions in the country. Fund allocations to statutory bodies like UGC, AICTE, have decreased, which means lesser money to state institutes and technical colleges. Rashtriya Uchchatar Shiksha Abhiyan (RUSA), which funds all the State universities and colleges has seen an allocation of INR 2,100 crore, which is about INR 700 crore more from last year. This is highly insufficient for the upgrade of educational institutes in the States that are in a pitiable condition. To fund major infrastructural projects through loan grants, last year Higher Education Financing Agency (HEFA) was allocated INR 2,750 crore, however that too has been reduced to INR 2,100 crore this year. HEFA also funds capital expenditure of the elite institutes that have been asked to allow 10% EWS quota and increase their intake capacity by 25%. These will need major revenue boost, that seems impossible from the current budget outlay. Fund allocation to central universities too have been reduced. The only major improvement in higher education seems to be the increase in salary scale for professors and funds allocated to research and innovation activities.
Greater gender integration, but decline in women-specific schemes
In the last budget before the national elections, Prime Minister Narendra Modi’s government pitched for transforming “women’s development to women-led development.” Adopted on the evidence-backed premise that gender-neutral policies lead to gender-unequal outcomes, India formally adopted Gender Responsive Budgeting (GRB) in 2005. Every budget since has included a statement that lists out two parts — Part A, which reflects ‘Women Specific Schemes’ which have 100% allocation for women, and Part B, which reflects ‘Pro Women Schemes’ where at least 30% of the allocation is for women.
On Friday, interim finance minister Piyush Goyal proposed to increase the budget allocation for the Mission for Protection and Empowerment for Women from INR 121,961 crore in 2018-19 to INR 131,700 crore for 2019-20, reflecting an overall increase of INR 174 crore. The mainstreaming of gender budgeting across sectors is demonstrable in the fact that more than 70% of beneficiaries of the Pradhan Mantri Mudra Yojana, which offers financial support to small and micro enterprises, were women. Similarly, the Ujjawala Yojana, which has already provided 6 crore free LPG connections, and aims to provide another 2 crore free connections by next year, has a very direct impact on homemakers, especially in rural areas. Further, an increase in budgetary allocation of schemes such as the National Rural Livelihood Mission (INR 4,512 crore), MGNREGA (INR 20,000 crore) and the PM’s employment generation programme (INR 2,327 crore) is also reflected in the gender budget.
The recognition of the cross-cutting nature of gender concerns and their firm integration in fiscal policies is good news. At the same time, it is noteworthy that the budgetary allocation on “women-specific schemes” has declined from INR 4,271.09 crore (budget estimates/BE) to INR 2,573.66 crore (revised estimates/RE) in 2018-19. Hence, an overall increase in the gender budget does necessarily translate into higher spending on women without careful implementation and gender audits.
Standard
More than three years after the Paris Agreement was finalised at COP21, it is evident that the developing world is unlikely to receive even the modest amount of US$100 billion annually in climate finance by 2020. This is primarily a result of the collective failure of the developed world to meet their moral and real climate obligations that pre-date the Paris Agreement. This lack of finance for climate action is exacerbated by the fact that the international financial community—banks, asset managers, investors and capital markets—have failed to align their operations with the goals of the Paris Agreement. The involvement of international financial investors, both private and multilateral, in financing green transitions in developing countries has so far been feeble, sporadic and arbitrary. Unless these resources can be leveraged to cater to the development needs of emerging economies, there is a real possibility that the green transitions that we all seek will be incomplete and mostly underwritten by the world’s poorest citizens.
For the past two years, ORF and the MacArthur Foundation have attempted to create a new framework to ensure that the global financial community better responds to the imperatives of the Paris Agreement. Our research acknowledges that official aid and grants are insufficient to meet the burgeoning energy and infrastructure needs of emerging economies. There is no doubt that we require new financial instruments and pipelines to support sustainable development in much of the world. This publication, comprising of 11 policy essays on the subject of climate finance, discusses this objective through multiple lenses. It is a culmination of our efforts to work with a global network of experts and stakeholders to identify bottlenecks and provide new solutions to ensure that emerging economies can access finance to meet their green development goals.
Our series on financing green transitions has largely focused on India, and for good reason: It will be the first large country that must transition to a middle-income economy in a fossil fuel-constrained world. India is also constricted by the same political, regulatory and financial challenges that confront much of the developing world. Given the weak efforts of the developed world to assist the developing countries so far, India has had to chart a path largely through its own economic and financial arrangements. Therefore, an assessment of India’s capacity to now leverage international financial flows and its ability to undertake a low-carbon transition may well provide a reliable template for developing countries to emulate.
Through 11 essays, we explore three broad themes: the role of international investors and institutions; India’s own development policy choices and lessons therein for other developing countries; and the role of human capital in climate-resilient investment.
Our first set of essays analyses the behaviour and financial practises of international financial institutions, investors and credit rating organisations. In “An Incomplete Transformation”, Mihir Sharma argues that Multilateral Development Banks have failed to create bridges between private capital and clean energy/climate resilient infrastructure demands in developing countries. He calls on MDBs to adapt to developing world priorities, crowd-in private capital, and streamline operational activities in emerging economies. In “Financing Climate Resilience”, Vikrom Mathur and Aparna Roy highlight the bias of international investors towards investing mostly in mitigation efforts. Conventional wisdom in the private sector holds that the costs of adaptation and resilience should be borne by governments. Taking a different approach to the problem, Mathur and Roy offer solutions focused on commercial and business opportunities. In two pieces, “Rating Resilience” and “Ratings for Renewable Energy”, Aled Jones studies the limitations of current literature and practices relating to credit rating of infrastructure projects and renewable energy projects and proposes a more holistic framework of risk metrics for both renewable energy and climate resilient infrastructure. Finally, in “The Political Economy of Basel”, Mihir Sharma outlines how the Basel norms have been designed to respond to the interests of a select group of developed nations. He argues that by prioritising macroeconomic stability and implementing new liquidity restrictions, these actors have failed to consider adverse implications on cross-border flows, especially with regards to long-term green investments.
The next set of essays focuses on India’s domestic challenges, particularly in its infrastructure and urban development policy and its efforts to transition to a low-carbon economy. In “PPP model, regulatory oversight and private financing: Evolutionary trinity of India’s infrastructure”, Gautam Chikermane offers a comprehensive historical account of the political economy of India’s infrastructure policy, documenting the many failures that have plagued it. Given that a stable infrastructure policy will have significant implications for green investment choices, Chikermane’s study of India’s policy failures provides valuable lessons. In “Financing Urban Infrastructure for an Evolving India”, Pritika Hingorani, Sharmadha Srinivasan, and Harshita Agarwal examine the reasons for the lack of private-sector involvement in India’s climate-resilient urban infrastructure. They analyse the current regulatory regime for urban infrastructure in India and provide a set of solutions, advancing both public and private sector participation in the future. In “Moving from Growth to Development: Financing Green Investment in India”, Neha Kumar, Prashant Vaze and Sean Kidney explore new financial instruments that India can employ to finance its green infrastructure needs. They outline how India can more effectively scale its green bonds market, leverage international debt capital markets, and harness blended finance to achieve this objective. Finally, in “India and the World,” Aparajit Pandey and I outline three key structural barriers that threaten to undermine India’s rapidly growing green energy sector: the state of its distribution companies, underdeveloped financial markets and inflexible international credit and risk assessment practices. Offering case studies from India’s state and municipal level policies, we argue that India’s ability to succeed in its low-carbon transition will open new pathways for emerging economies around the world.
In our final set of essays, we examine the role of human capital in enabling greater green investment, focusing on leadership and gender. In “Pay for Sustainable Growth”, Charanjit Singh, analyses the executive pay of 31 of India’s top companies showing that by linking management compensation to short-term performance objective, companies are failing to integrate sustainability objectives into their long-term vision. The chapter proposes a restructuring of the private sector’s approach to executive compensation, focused on long-term sustainable economic growth. Lastly, in “Gender and Climate Finance,” Vidisha Mishra posits that even though women and marginalised groups are likely to be more exposed to climate change related risks, they are severely underrepresented in the investment and regulatory classes. Her essay then unpacks the opportunities and benefits of meaningfully building gender concerns into climate finance mechanisms.
Our contributors have attempted to explore the reasons behind the significant shortfall in private finance in relation to low-carbon investments. They have also collectively offered solutions, both domestic and international, with regards to the flow of finance for climate projects. The success of these solutions, however, will be predicated on some boundary conditions that developing economies and the international financial community must meet.
First, developing countries must reclaim the power grid. The large-scale subsidisation of power in the developing world has created significant distortions in energy use, pricing and policy. State-level reform in India suggests that splitting the electrical grid for agricultural and non-agricultural sectors, implementing a credible metering system and providing subsidies as direct benefits can have significant positive effects on the power sector. Without a viable grid, green investments are likely to remain unviable.
The second is to build capacity amongst international investors to understand risk and opportunity in developing states. There is generally a bias stemming from lack of knowledge (information) and capacity (human resources) to assess risks in emerging economies. This ultimately translates into an inability to understand the economic landscape of recipient countries. Further, as one of our authors has highlighted, there are few institutional attempts at gendering climate investments and finance. A lack of female representation in the investor community, especially from the developing world, invariably means that the concerns and voices of the most vulnerable are ignored as financial plans are scripted.
Third, developing countries must build innovative policy tools to leverage new financial instruments and mechanisms. Currently, regulations related to debt and equity markets restrict the flow of international capital into climate action projects. Emerging economies must co-opt their financial sector in the fight against climate change. Financial markets that allow for debt financing and locally issued green bonds for example create a diverse set of instruments that different types on investors can rely on. More ambitious measures can include the creation of a “green investment bank,” which allow the crowding in of private investment in green assets.
Finally, there is a new imperative to overhaul regulatory systems around the world, both in recipient and investing states. Vast pools of money are held by multiple categories of investors, such as pension funds and insurance companies. However, existing regulations limit the ability of fund managers to invest in climate related projects. Further, international credit rating agencies reassess the methodology for assessments of green projects in developing countries. And perhaps most importantly, there is an urgent need to review the current set of Basel Accords as well as the next iteration of Basel IV accords. The macro-prudential regulations were designed to create a more risk-free international banking system but have unintentionally stymied the ability of the financial sector to contribute to climate resilience. The banking community must acknowledge that planetary risk is the largest systemic challenge to financial stability and that mitigating such risk is the most prudential practice.
While these solutions are far from comprehensive, they address some of the most persistent structural barriers to supplying and accessing climate finance. ORF and the MacAuthur Foundation will continue to explore new ways and means to ensure that developing countries can access financing to pursue their low-carbon transitions. We will also continue to study India’s own financial, technological and governance solutions in the hope that these experiences can benefit other countries and communities. We hope that the insights presented in this book will inform academics, business leaders and policymakers in their efforts to better understand the importance of the global financial community finally signing the Paris Agreement.
Read here – orfonline.org/research/financing-green-transitions-47553/
More than three years after the Paris Agreement was finalised at COP21, it is evident that the developing world is unlikely to receive even the modest amount of US$100 billion annually in climate finance by 2020. This is primarily a result of the collective failure of the developed world to meet their moral and real climate obligations that pre-date the Paris Agreement. This lack of finance for climate action is exacerbated by the fact that the international financial community—banks, asset managers, investors and capital markets—have failed to align their operations with the goals of the Paris Agreement. The involvement of international financial investors, both private and multilateral, in financing green transitions in developing countries has so far been feeble, sporadic and arbitrary. Unless these resources can be leveraged to cater to the development needs of emerging economies, there is a real possibility that the green transitions that we all seek will be incomplete and mostly underwritten by the world’s poorest citizens.
For the past two years, ORF and the MacArthur Foundation have attempted to create a new framework to ensure that the global financial community better responds to the imperatives of the Paris Agreement. Our research acknowledges that official aid and grants are insufficient to meet the burgeoning energy and infrastructure needs of emerging economies. There is no doubt that we require new financial instruments and pipelines to support sustainable development in much of the world. This publication, comprising of 11 policy essays on the subject of climate finance, discusses this objective through multiple lenses. It is a culmination of our efforts to work with a global network of experts and stakeholders to identify bottlenecks and provide new solutions to ensure that emerging economies can access finance to meet their green development goals.
Our series on financing green transitions has largely focused on India, and for good reason: It will be the first large country that must transition to a middle-income economy in a fossil fuel-constrained world. India is also constricted by the same political, regulatory and financial challenges that confront much of the developing world. Given the weak efforts of the developed world to assist the developing countries so far, India has had to chart a path largely through its own economic and financial arrangements. Therefore, an assessment of India’s capacity to now leverage international financial flows and its ability to undertake a low-carbon transition may well provide a reliable template for developing countries to emulate.
Through 11 essays, we explore three broad themes: the role of international investors and institutions; India’s own development policy choices and lessons therein for other developing countries; and the role of human capital in climate-resilient investment.
Our first set of essays analyses the behaviour and financial practises of international financial institutions, investors and credit rating organisations. In “An Incomplete Transformation”, Mihir Sharma argues that Multilateral Development Banks have failed to create bridges between private capital and clean energy/climate resilient infrastructure demands in developing countries. He calls on MDBs to adapt to developing world priorities, crowd-in private capital, and streamline operational activities in emerging economies. In “Financing Climate Resilience”, Vikrom Mathur and Aparna Roy highlight the bias of international investors towards investing mostly in mitigation efforts. Conventional wisdom in the private sector holds that the costs of adaptation and resilience should be borne by governments. Taking a different approach to the problem, Mathur and Roy offer solutions focused on commercial and business opportunities. In two pieces, “Rating Resilience” and “Ratings for Renewable Energy”, Aled Jones studies the limitations of current literature and practices relating to credit rating of infrastructure projects and renewable energy projects and proposes a more holistic framework of risk metrics for both renewable energy and climate resilient infrastructure. Finally, in “The Political Economy of Basel”, Mihir Sharma outlines how the Basel norms have been designed to respond to the interests of a select group of developed nations. He argues that by prioritising macroeconomic stability and implementing new liquidity restrictions, these actors have failed to consider adverse implications on cross-border flows, especially with regards to long-term green investments.
The next set of essays focuses on India’s domestic challenges, particularly in its infrastructure and urban development policy and its efforts to transition to a low-carbon economy. In “PPP model, regulatory oversight and private financing: Evolutionary trinity of India’s infrastructure”, Gautam Chikermane offers a comprehensive historical account of the political economy of India’s infrastructure policy, documenting the many failures that have plagued it. Given that a stable infrastructure policy will have significant implications for green investment choices, Chikermane’s study of India’s policy failures provides valuable lessons. In “Financing Urban Infrastructure for an Evolving India”, Pritika Hingorani, Sharmadha Srinivasan, and Harshita Agarwal examine the reasons for the lack of private-sector involvement in India’s climate-resilient urban infrastructure. They analyse the current regulatory regime for urban infrastructure in India and provide a set of solutions, advancing both public and private sector participation in the future. In “Moving from Growth to Development: Financing Green Investment in India”, Neha Kumar, Prashant Vaze and Sean Kidney explore new financial instruments that India can employ to finance its green infrastructure needs. They outline how India can more effectively scale its green bonds market, leverage international debt capital markets, and harness blended finance to achieve this objective. Finally, in “India and the World,” Aparajit Pandey and I outline three key structural barriers that threaten to undermine India’s rapidly growing green energy sector: the state of its distribution companies, underdeveloped financial markets and inflexible international credit and risk assessment practices. Offering case studies from India’s state and municipal level policies, we argue that India’s ability to succeed in its low-carbon transition will open new pathways for emerging economies around the world.
In our final set of essays, we examine the role of human capital in enabling greater green investment, focusing on leadership and gender. In “Pay for Sustainable Growth”, Charanjit Singh, analyses the executive pay of 31 of India’s top companies showing that by linking management compensation to short-term performance objective, companies are failing to integrate sustainability objectives into their long-term vision. The chapter proposes a restructuring of the private sector’s approach to executive compensation, focused on long-term sustainable economic growth. Lastly, in “Gender and Climate Finance,” Vidisha Mishra posits that even though women and marginalised groups are likely to be more exposed to climate change related risks, they are severely underrepresented in the investment and regulatory classes. Her essay then unpacks the opportunities and benefits of meaningfully building gender concerns into climate finance mechanisms.
Our contributors have attempted to explore the reasons behind the significant shortfall in private finance in relation to low-carbon investments. They have also collectively offered solutions, both domestic and international, with regards to the flow of finance for climate projects. The success of these solutions, however, will be predicated on some boundary conditions that developing economies and the international financial community must meet.
First, developing countries must reclaim the power grid. The large-scale subsidisation of power in the developing world has created significant distortions in energy use, pricing and policy. State-level reform in India suggests that splitting the electrical grid for agricultural and non-agricultural sectors, implementing a credible metering system and providing subsidies as direct benefits can have significant positive effects on the power sector. Without a viable grid, green investments are likely to remain unviable.
The second is to build capacity amongst international investors to understand risk and opportunity in developing states. There is generally a bias stemming from lack of knowledge (information) and capacity (human resources) to assess risks in emerging economies. This ultimately translates into an inability to understand the economic landscape of recipient countries. Further, as one of our authors has highlighted, there are few institutional attempts at gendering climate investments and finance. A lack of female representation in the investor community, especially from the developing world, invariably means that the concerns and voices of the most vulnerable are ignored as financial plans are scripted.
Third, developing countries must build innovative policy tools to leverage new financial instruments and mechanisms. Currently, regulations related to debt and equity markets restrict the flow of international capital into climate action projects. Emerging economies must co-opt their financial sector in the fight against climate change. Financial markets that allow for debt financing and locally issued green bonds for example create a diverse set of instruments that different types on investors can rely on. More ambitious measures can include the creation of a “green investment bank,” which allow the crowding in of private investment in green assets.
Finally, there is a new imperative to overhaul regulatory systems around the world, both in recipient and investing states. Vast pools of money are held by multiple categories of investors, such as pension funds and insurance companies. However, existing regulations limit the ability of fund managers to invest in climate related projects. Further, international credit rating agencies reassess the methodology for assessments of green projects in developing countries. And perhaps most importantly, there is an urgent need to review the current set of Basel Accords as well as the next iteration of Basel IV accords. The macro-prudential regulations were designed to create a more risk-free international banking system but have unintentionally stymied the ability of the financial sector to contribute to climate resilience. The banking community must acknowledge that planetary risk is the largest systemic challenge to financial stability and that mitigating such risk is the most prudential practice.
While these solutions are far from comprehensive, they address some of the most persistent structural barriers to supplying and accessing climate finance. ORF and the MacAuthur Foundation will continue to explore new ways and means to ensure that developing countries can access financing to pursue their low-carbon transitions. We will also continue to study India’s own financial, technological and governance solutions in the hope that these experiences can benefit other countries and communities. We hope that the insights presented in this book will inform academics, business leaders and policymakers in their efforts to better understand the importance of the global financial community finally signing the Paris Agreement.
More than three years after the Paris Agreement was finalised at COP21, it is evident that the developing world is unlikely to receive even the modest amount of US$100 billion annually in climate finance by 2020. This is primarily a result of the collective failure of the developed world to meet their moral and real climate obligations that pre-date the Paris Agreement. This lack of finance for climate action is exacerbated by the fact that the international financial community—banks, asset managers, investors and capital markets—have failed to align their operations with the goals of the Paris Agreement. The involvement of international financial investors, both private and multilateral, in financing green transitions in developing countries has so far been feeble, sporadic and arbitrary. Unless these resources can be leveraged to cater to the development needs of emerging economies, there is a real possibility that the green transitions that we all seek will be incomplete and mostly underwritten by the world’s poorest citizens.
For the past two years, ORF and the MacArthur Foundation have attempted to create a new framework to ensure that the global financial community better responds to the imperatives of the Paris Agreement. Our research acknowledges that official aid and grants are insufficient to meet the burgeoning energy and infrastructure needs of emerging economies. There is no doubt that we require new financial instruments and pipelines to support sustainable development in much of the world. This publication, comprising of 11 policy essays on the subject of climate finance, discusses this objective through multiple lenses. It is a culmination of our efforts to work with a global network of experts and stakeholders to identify bottlenecks and provide new solutions to ensure that emerging economies can access finance to meet their green development goals.
Our series on financing green transitions has largely focused on India, and for good reason: It will be the first large country that must transition to a middle-income economy in a fossil fuel-constrained world. India is also constricted by the same political, regulatory and financial challenges that confront much of the developing world. Given the weak efforts of the developed world to assist the developing countries so far, India has had to chart a path largely through its own economic and financial arrangements. Therefore, an assessment of India’s capacity to now leverage international financial flows and its ability to undertake a low-carbon transition may well provide a reliable template for developing countries to emulate.
Through 11 essays, we explore three broad themes: the role of international investors and institutions; India’s own development policy choices and lessons therein for other developing countries; and the role of human capital in climate-resilient investment.
Our first set of essays analyses the behaviour and financial practises of international financial institutions, investors and credit rating organisations. In “An Incomplete Transformation”, Mihir Sharma argues that Multilateral Development Banks have failed to create bridges between private capital and clean energy/climate resilient infrastructure demands in developing countries. He calls on MDBs to adapt to developing world priorities, crowd-in private capital, and streamline operational activities in emerging economies. In “Financing Climate Resilience”, Vikrom Mathur and Aparna Roy highlight the bias of international investors towards investing mostly in mitigation efforts. Conventional wisdom in the private sector holds that the costs of adaptation and resilience should be borne by governments. Taking a different approach to the problem, Mathur and Roy offer solutions focused on commercial and business opportunities. In two pieces, “Rating Resilience” and “Ratings for Renewable Energy”, Aled Jones studies the limitations of current literature and practices relating to credit rating of infrastructure projects and renewable energy projects and proposes a more holistic framework of risk metrics for both renewable energy and climate resilient infrastructure. Finally, in “The Political Economy of Basel”, Mihir Sharma outlines how the Basel norms have been designed to respond to the interests of a select group of developed nations. He argues that by prioritising macroeconomic stability and implementing new liquidity restrictions, these actors have failed to consider adverse implications on cross-border flows, especially with regards to long-term green investments.
The next set of essays focuses on India’s domestic challenges, particularly in its infrastructure and urban development policy and its efforts to transition to a low-carbon economy. In “PPP model, regulatory oversight and private financing: Evolutionary trinity of India’s infrastructure”, Gautam Chikermane offers a comprehensive historical account of the political economy of India’s infrastructure policy, documenting the many failures that have plagued it. Given that a stable infrastructure policy will have significant implications for green investment choices, Chikermane’s study of India’s policy failures provides valuable lessons. In “Financing Urban Infrastructure for an Evolving India”, Pritika Hingorani, Sharmadha Srinivasan, and Harshita Agarwal examine the reasons for the lack of private-sector involvement in India’s climate-resilient urban infrastructure. They analyse the current regulatory regime for urban infrastructure in India and provide a set of solutions, advancing both public and private sector participation in the future. In “Moving from Growth to Development: Financing Green Investment in India”, Neha Kumar, Prashant Vaze and Sean Kidney explore new financial instruments that India can employ to finance its green infrastructure needs. They outline how India can more effectively scale its green bonds market, leverage international debt capital markets, and harness blended finance to achieve this objective. Finally, in “India and the World,” Aparajit Pandey and I outline three key structural barriers that threaten to undermine India’s rapidly growing green energy sector: the state of its distribution companies, underdeveloped financial markets and inflexible international credit and risk assessment practices. Offering case studies from India’s state and municipal level policies, we argue that India’s ability to succeed in its low-carbon transition will open new pathways for emerging economies around the world.
In our final set of essays, we examine the role of human capital in enabling greater green investment, focusing on leadership and gender. In “Pay for Sustainable Growth”, Charanjit Singh, analyses the executive pay of 31 of India’s top companies showing that by linking management compensation to short-term performance objective, companies are failing to integrate sustainability objectives into their long-term vision. The chapter proposes a restructuring of the private sector’s approach to executive compensation, focused on long-term sustainable economic growth. Lastly, in “Gender and Climate Finance,” Vidisha Mishra posits that even though women and marginalised groups are likely to be more exposed to climate change related risks, they are severely underrepresented in the investment and regulatory classes. Her essay then unpacks the opportunities and benefits of meaningfully building gender concerns into climate finance mechanisms.
Our contributors have attempted to explore the reasons behind the significant shortfall in private finance in relation to low-carbon investments. They have also collectively offered solutions, both domestic and international, with regards to the flow of finance for climate projects. The success of these solutions, however, will be predicated on some boundary conditions that developing economies and the international financial community must meet.
First, developing countries must reclaim the power grid. The large-scale subsidisation of power in the developing world has created significant distortions in energy use, pricing and policy. State-level reform in India suggests that splitting the electrical grid for agricultural and non-agricultural sectors, implementing a credible metering system and providing subsidies as direct benefits can have significant positive effects on the power sector. Without a viable grid, green investments are likely to remain unviable.
The second is to build capacity amongst international investors to understand risk and opportunity in developing states. There is generally a bias stemming from lack of knowledge (information) and capacity (human resources) to assess risks in emerging economies. This ultimately translates into an inability to understand the economic landscape of recipient countries. Further, as one of our authors has highlighted, there are few institutional attempts at gendering climate investments and finance. A lack of female representation in the investor community, especially from the developing world, invariably means that the concerns and voices of the most vulnerable are ignored as financial plans are scripted.
Third, developing countries must build innovative policy tools to leverage new financial instruments and mechanisms. Currently, regulations related to debt and equity markets restrict the flow of international capital into climate action projects. Emerging economies must co-opt their financial sector in the fight against climate change. Financial markets that allow for debt financing and locally issued green bonds for example create a diverse set of instruments that different types on investors can rely on. More ambitious measures can include the creation of a “green investment bank,” which allow the crowding in of private investment in green assets.
Finally, there is a new imperative to overhaul regulatory systems around the world, both in recipient and investing states. Vast pools of money are held by multiple categories of investors, such as pension funds and insurance companies. However, existing regulations limit the ability of fund managers to invest in climate related projects. Further, international credit rating agencies reassess the methodology for assessments of green projects in developing countries. And perhaps most importantly, there is an urgent need to review the current set of Basel Accords as well as the next iteration of Basel IV accords. The macro-prudential regulations were designed to create a more risk-free international banking system but have unintentionally stymied the ability of the financial sector to contribute to climate resilience. The banking community must acknowledge that planetary risk is the largest systemic challenge to financial stability and that mitigating such risk is the most prudential practice.
While these solutions are far from comprehensive, they address some of the most persistent structural barriers to supplying and accessing climate finance. ORF and the MacAuthur Foundation will continue to explore new ways and means to ensure that developing countries can access financing to pursue their low-carbon transitions. We will also continue to study India’s own financial, technological and governance solutions in the hope that these experiences can benefit other countries and communities. We hope that the insights presented in this book will inform academics, business leaders and policymakers in their efforts to better understand the importance of the global financial community finally signing the Paris Agreement.
Every year, the Raisina Dialogue convenes experts from a diverse cross-section of disciplines and professions to address the most challenging issues facing the global community. It is fair to say that for the past few years, the common sentiment is that we live in an age of “disruption,” given the upheavals that have characterized global politics over the last decade. As the dialogue prepares to convene once again in 2019, the world is evolving in response to these disruptions. Older systems of management are straining or already broken, but the new regimes, rules, and concepts that could replace them are still forming. This year, Raisina will take stock of the immediate consequences of these disruptions, and explore how these consequences inform our visions of the emerging world order.
The redrawing of our mental maps of the world is perhaps the most consequential development. The tensions and instability emanating from North America and Europe have reinforced the fragility of the Atlantic system: that it won’t be able to sustain its role as the lynchpin of the international order.
Each successive year in the last decade has brought with it disruptions implicating global politics, economics and societies. At the Raisina Dialogue last year, we discussed how best to manage such disruptive transitions. This year, we believe that it is time to look ahead and search for new solutions and frameworks to manage the world. A “World Reorder” is our theme for Raisina 2019—and bold as it maybe, we have little doubt that the moment to reflect on this is already upon us.
Perhaps the most important driver of change is the certainty that 2019 will herald the arrival of truly global politics. The post-war order contributed immensely to the progress and security of nations; yet its ideas, frameworks and institutions are no longer sufficient for a new world.
The small community of nations that designed and sustained it must give way to a more diverse constellation of actors. New powers from the East are only one set of stakeholders—increasingly, global governance must allow for distribution of authority and agency to a more diffused networks of actors, from cities and citizens to corporations and civil society organisations. How we do this will be the key question of our time.
Consequently, we have chosen five themes that are defining a new world order. Perhaps the most consequential of these developments is the emergence of new strategic geographies that are transcending the old divides of East, West, North and South. Second, we analyse the discontent with today’s globalisation paradigms—and how new trade and technology tensions are threatening the future of connectivity and commerce. Third, we explore how technology is compelling us to search for a new contract between the individual, business and the state. Fourth, we ask what ethics will define the development and deployment of new technologies and how they will affect individuals and our societies. Finally, we emphasise the role of leadership—both individual and institutional—in managing the complexities of today’s world.
These are the big ideas that have influenced the design of the Raisina Dialogue 2019. Over the next three days, we have curated over 40 sets of interactions with a global community of leaders and experts in an attempt to paint a picture of a new world order that is rapidly emerging.
A prominent feature of this year’s conversation at Raisina is Europe or more broadly, Eurasia. This supercontinent is without doubt the most dynamic and unpredictable region in the world, one that continues to surprise itself and others around it. Once considered a benchmark for democracy and collective security, the EU is today increasingly roiled by the politics and economics of populism. Equally significant is that the geographical construct of the larger European continent is dissipating. New flows of finance, labour and information are merging Asia and Europe into a single Eurasian supercontinent. The question for the EU and other European actors, therefore, is whether they can act upon these momentous changes or be subsumed by them.
The waters that link this region are undergoing a churn as well. Strategic and economic drivers have brought about seminal changes in the Arctic and the Indo-Pacific.
As climate change transforms the geography of the Arctic, its waters will merge the politics of the Pacific and the Atlantic Ocean, even as the regions’ incumbent powers scramble to create new arrangements. The Indo-Pacific, meanwhile, is already fast becoming a domain for great power competition. Yet, with over 60 percent of the world’s populations residing astride these waters, its potential for scripting new paradigms for globalisation and development is unparalleled. This begs the question, then, of whether these new constructs merely allow us to visualise and manage tensions in the region, or whether they can emerge as a new conduit for development and stability.
The emergence of these new geographies is no coincidence. They are symptoms of a new normal in global politics—the eastward tilt in the concentration of economic wealth and military might. Two prominent questions arise from this trend. For one, what does this mean for the West? Can the liberal international order remain viable even as Western values, norms and influence steadily decline in international affairs? Second, what is the future of governance in Asia? The rise of new powers and interests is necessitating the ideation of new norms and institutions; however, there is little consensus on how to go about this process as old tensions eclipse the potential for cooperation.
The broader shift in economic power will certainly not be free of friction. Indeed, it has already given rise to tensions amongst the great powers of the West and the East.
Both the US and China are exerting their influence upon the rules of trade and commerce—and technology is the flashpoint that may inject a new urgency and ferocity to this contest. This dispute is only one facet of the broader dissatisfaction buffeting the global economic order. The rise of non-market economies and the domestic compulsions of populism and nativist economics are threatening the very foundations of free markets and free trade. How will the economic order that has enabled much prosperity over the past seven decades adapt? More consequentially, what happens if it cannot?
Even as the very foundations of the global order stand on shaky ground, the world is still attempting to address the imperatives of sustainable development. Emerging economies are struggling to access and raise sufficient finance to fuel their sustainable development pathways, while trillions of dollars remain locked up in Western pension funds and insurance schemes. This hints at a deeper issue: that 20th-century development paradigms continue to privilege a small set of actors and reflect their biases, preventing flows of technology and finance where they are most needed. Indeed, we must continue to ask how the global development agenda can be made more diverse by accommodating new voices. Engendering conversations on globalisation and development is certainly one solution; and it must form part of the template that includes underrepresented communities from around the world.
It is time that voices from the dynamic African continent contribute to the deliberations on the future of growth and development; and Latin American perspectives add a new dimension to the voice of America.
For many years, the world remained optimistic that new technologies would provide a voice to these communities and create new pathways for progress. Events in 2018 have compelled us to revisit this consensus. Balancing the imperatives of economic growth, national security and privacy seems harder than ever before. Democracies, it appears, are hard-pressed to achieve this, given that open societies are most vulnerable to manipulation and influence in their political processes. Worryingly, however, despite their outsized influence in our lives, global technology platforms have proven immune to calls for accountability and reform. This year, therefore, the Raisina Dialogue will ask how powerful technology companies can be made more accountable to the constituencies that drive their growth and profit. Or else must we rethink regulation that curtails their influence and reach?
There is, however, little doubt that technology will continue to transform our societies. The fourth industrial revolution will spur new breakthrough innovations and progress, even as it makes redundant extant arrangements for social mobility and economic growth. It will also compel us to reimagine the value of human capital. Our education, healthcare and labour frameworks must shed their 20th-century formats and reflect the realities of today’s knowledge-based information economy. Further, societies will have to grapple with creating ethical frameworks for new technologies as they increasingly become essential to our politics, economics and military postures. In today’s polarised times, these tasks will not be easy.
This year at Raisina, we also explore an often-ignored aspect of governance; one that will be increasingly relevant in today’s complex world: leadership.
In a world buffeted by multiple headwinds, it appears that we are experiencing a dearth of progressive leadership. How can individuals and institutions rise above the political divides that are inhibiting a new consensus?
Finally, we explore the role of India on the global high table. The opening lines of the Mahabharat, one of India’s oldest epics, boldly states that knowledge that eludes its pages may not be found elsewhere. It is fair to aver that India shares the same relationship with the world. Its billion-plus population is an embodiment of all that is right with the world and all that needs resolution. The challenges that it confronts are those that constrain all of us today. It is inexorably destined to be the steward of the liberal order with which it has had significant differences in the past. It is still emerging even as it leads, it raises hopes even as it disappoints. Indeed, India is a “boundary” nation. It is a living experiment where science and religion and identities and ideas intermingle to script a unique narrative of progress.
It is therefore an ideal location to dissect the most important issues that engage us all. It is on these boundaries that durable pathways for a world reorder will be discovered. This year, we have convened over 40 conversations to assess, analyse and argue these emerging realities. With 1,500 participants including 600 delegates and speakers from over 92 countries converging in New Delhi, there will be ample diversity and plurality of opinion. And our concerted efforts towards achieving gender parity have ensured that women account for over 40 percent of our delegates this year.
We hope that the Raisina Dialogue can be an incubator that generates new ideas for a shared planet and our common future; provide a space where contesting ideas can flow freely; and a platform where we may just tease out an elusive consensus. As always, we look forward to hosting you here in New Delhi.
नार्वे की प्रधानमंत्री महामहिम, सुश्री एर्ना सोलबर्ग;
भारत के माननीय प्रधानमंत्री, श्री नरेन्द्र मोदी जी;
माननीय विदेश मंत्री श्रीमती सुषमा स्वराज जी;
मंत्रिगणों, एडमिरल्स, जनरल्स और दुनिया भर से आए प्रतिष्ठित नेतागणों; तथा हमारे प्रतिनिधियों और प्रतिभागियों
रायसीना डायलॉग के चौथे संस्करण में आपका स्वागत है।
हमारे ऑनलाइन ऑडीअन्स का भी खासतौर पर अभिनंदन — मुझे बताया गया है कि पिछले साल उनकी संख्या 3 मिलियन से ज्यादा थी।
हमें उम्मीद है कि इस साल यह संख्या और भी ज्यादा होगी, क्योंकि इस बार हम रायसीना को मराठी और हिंदी में ट्वीट और कवर करेंगे तथा प्रतिदिन हिंदी में ‘बेस्ट आफ रायसीना’ वीडियो तैयार करेंगे।
मैं 92 देशों से आए 600 प्रतिनिधियों और वक्ताओं का हार्दिक स्वागत करता हूं, जो नई दिल्ली में हमारे साथ 50 घंटे की बहस और चर्चाओं में शामिल रहने वाले हैं। हमें इस बात की खासतौर पर खुशी है कि आज हमारे बीच काफी संख्या में वुमन लीडर्स और वक्ता मौजूद हैं — समस्त प्रतिनिधियों और वक्ताओं में से 40 प्रतिशत से अधिक महिलाएं हैं। अगले साल हम इस दिशा में बराबरी लाने की कोशिश करेंगे।
हमें अफ्रीका से पधारे 58 प्रतिनिधियों का स्वागत करते हुए हमें बेहद खुशी हो रही है — एक महाद्वीप, जिसकी आवाज को आवश्यक तौर पर हमारे भविष्य को बहुत अधिक प्रभावित करना चाहिए। हम अफ्रीका के साथ मजबूत रिश्ते बनाने के इच्छुक हैं — और 10 जनवरी को आप इस रोचक महाद्वीप में एक ग्लोबल डिवेलपमेंट प्लेटफॉर्म की मेजबानी करने की हमारी योजनाओं को जानेंगे।
रायसीना यंग फैलोज़ का तहेदिल से स्वागत। इस साल 29 देशों के 48 यंग लीडर्स यहां पधारे हैं — जो अपने देश की सरकार, मीडिया, व्यापार और सिविल सोसायटी के बेहतरीन प्रतिनिधि हैं। मुझे यह बताते हुए खुशी हो रही है कि इनमें आधे से अधिक युवतियां हैं। ये लगभग 1,500 पूर्व सदस्यों के लगातार बढ़ रहे नेटवर्क में शामिल हो जाएंगे, जिनमें से 100 से अधिक सदस्य इस साल फिर से हमारे साथ जुड़ने जा रहे हैं।
हमने इस मंच पर 200 छात्रों और युवा विचारकों को भी आमंत्रित किया है, जिनमें रूस का एक युवा प्रतिनिधिमंडल शामिल है। हम इस समूह का तहेदिल से स्वागत करते हैं और उस दुनिया के बारे में इनके विचार जानने को उत्सुक हैं, जो इन लोगों को विरासत में मिलने वाली है। हम अपने मंच को अलग बनाना चाहते हैं — हम इसे एक ऐसा स्थान बनाने की कोशिश कर रहे हैं, जहां युवाओं के विचार भविष्य में होने वाले विचार-विमर्शों को आकार दे सके।
हम इस साल रायसीना में होने वाली बातचीत और विचार-विमर्श में आप सभी का स्वागत करते हैं!
इस साल हम 80 से ज्यादा चर्चाओं का आयोजन करने जा रहे हैं: अगले तीन दिन तक 41 पैनल्स, 7 प्रमुख भाषणों, 3 अनौपचारिक वार्तालाप, 25 से अधिक स्टूडियो पैनल्स और 9 संबद्ध कार्यक्रमों का आयोजन किया जाएगा।
मैंने और मेरे सहयोगियों ने ऐसा वातावरण बनाने का प्रयास किया है, जो विविधता और प्रतिभा की दृष्टि से समृद्ध हो तथा चर्चा और विचार-विमर्श के लिए अनुकूल हो।
मुझे यकीन है कि अगले दो दिन जानकारी और उत्साह से भरपूर होंगे, और निश्चित रूप से उन प्रस्तावों और साझेदारियों के रूप में परिणत होंगे, जिनसें हमें हमारी गतिशील और जटिल दुनिया का मार्गदर्शन करने में मदद मिलेगी।
रायसीना डायलॉग 2019 में आपका तहेदिल से स्वागत है!
मैं प्रारंभिक उद्बोधन के लिए ORF के अध्यक्ष श्री संजय जोशी का स्वागत करता हूं।